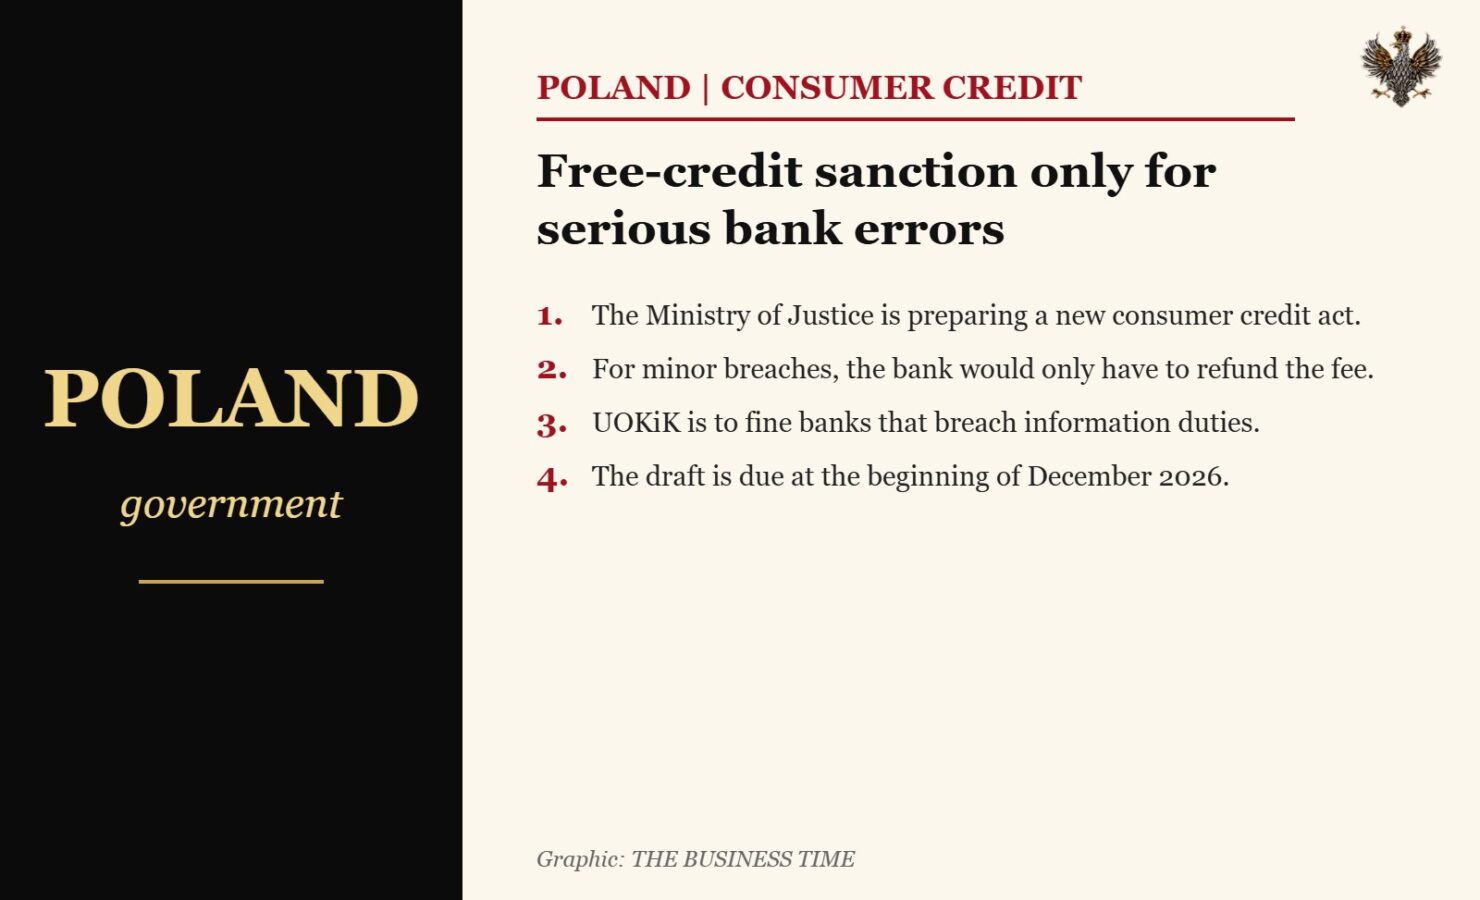
The Ministry of Justice, headed by Waldemar Żurek, is working on a new consumer credit act. Unofficial assumptions presented to banks and borrowers on 22 October show that the free-credit sanction (SKD) is to apply only to the most serious errors by banks.
SKD is a customer’s right to repay only the capital, without interest and fees, when a bank has misinformed them about the loan terms. Under the ministry’s plan, the sanction would apply, among other cases, when a bank failed to state the total cost of credit or the interest rate at all, or charged a commission in breach of the law. For lesser breaches, such as an unjustified fee, the bank would only have to refund that fee.
UOKiK (the Office of Competition and Consumer Protection) is to get a bigger role. It would conduct proceedings and fine banks that breach information duties towards many customers at once. The draft is to be published at the beginning of December 2026. It is still waiting to be entered on the government’s list of legislative work.
The draft was previously prepared by UOKiK, but in May Prime Minister Donald Tusk handed the work to the Ministry of Justice. The new rules are to implement the EU consumer credit directive (CCD2), which is due to apply from 20 November 2026. Poland will not meet this deadline – the ministry has informed the European Commission. According to the industry website CHF24, the new act is to cover loans of up to €100,000, and its adoption is planned by the end of the Sejm’s term in autumn 2027.
What it means for Poles in the UK
Many Poles in Britain are still repaying cash or instalment loans taken out in Poland. Law firms and claims companies often encourage SKD lawsuits. The new rules are not yet in force, and their final wording is not known. If you are considering such a claim, check your agreement now and ask a lawyer how the changes might affect your situation.
Our assessment
The direction is clear: fewer court disputes over minor errors, more penalties imposed by the regulator. This is good news for banks and worse news for some borrowers. The details may still change during consultations and in the Sejm.
What to do
- Find your loan agreement and check whether it states the total cost and the interest rate.
- Do not sign an agreement with a claims company without checking its fee.
- Free information: UOKiK and consumer ombudsmen.
Source: Rzeczpospolita (23 October 2026, updated 26 October 2026); CHF24.pl.
We assess factual corrections and substantive responses. Verified changes are reflected in our reporting.
Contact the editorial desk →